Smart money in the fall: what FIIs sold and Indian funds bought
Foreigners pulled a record ₹3.08 lakh crore out of Indian stocks in 2026. Indian funds took the shares. Who bought what, which results backed it, and where the signals agree.
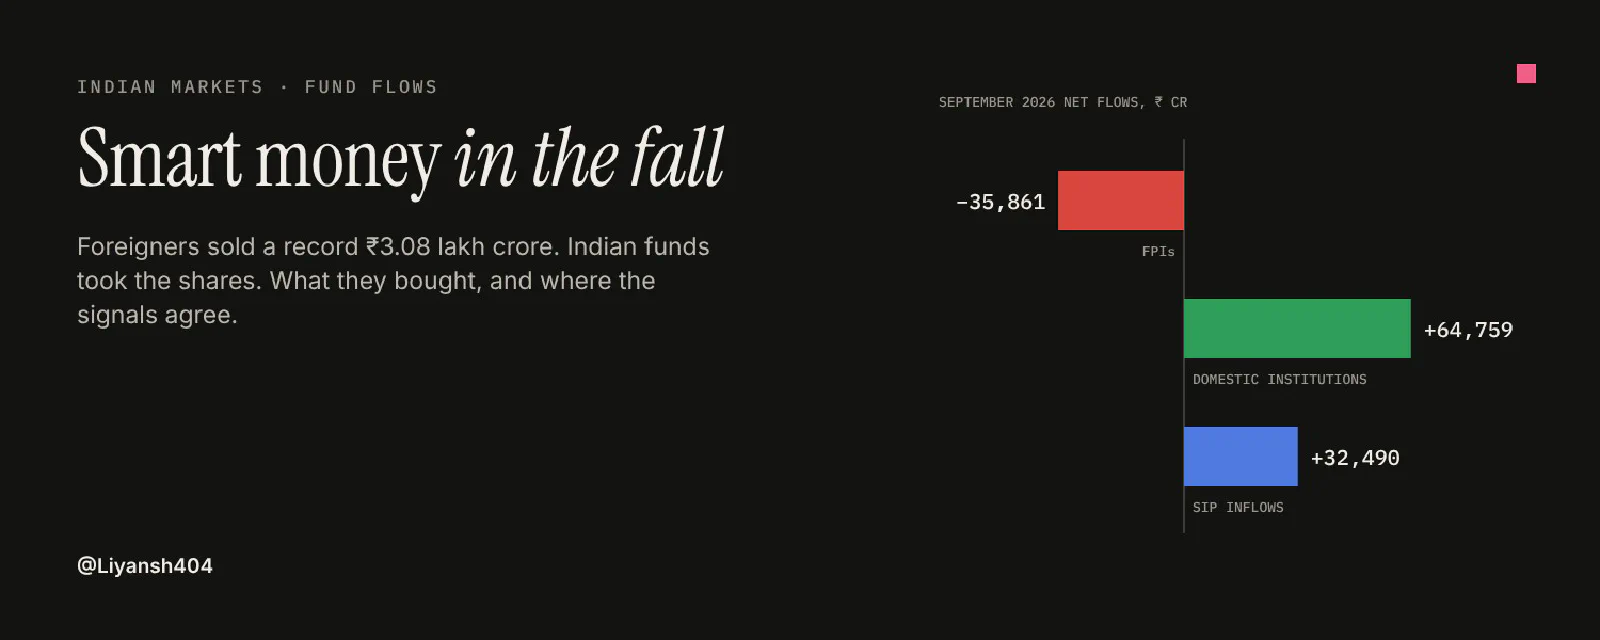
The answer in one minute
- Foreigners are selling and Indian funds are buying. FPIs sold a record ₹3.08 lakh crore of Indian equities in 2026 so far, including ₹35,861 crore in September and ₹48,056 crore in October to date. Domestic institutions bought ₹64,759 crore in September alone. SIPs hit a record ₹32,490 crore a month.
- The biggest trade is a handover in large caps. FIIs cut stakes and mutual funds took the shares:
- HDFC Bank: FIIs −2.4 points, domestic institutions +1.7.
- BSE, MCX and Swiggy saw the same pattern.
- So did Bharti Airtel, M&M, Muthoot Finance and Indus Towers.
- In ITC’s ₹9,395 crore block deal, GQG sold and Fidelity plus four Indian fund houses bought.
- Where both FIIs and Indian institutions added, the list is mostly new-age platforms and special situations:
- New listings: Lenskart, Meesho, Groww, Pine Labs.
- Thyrocare, Karnataka Bank and Apar Industries.
- Shares that changed hands from a promoter or private-equity seller: EPL, Torrent Pharma, Adani Enterprises.
- The one sector FPIs bought in October is IT (+₹2,599 crore in 1–15 Oct), led by HCL Tech, Tech Mahindra and Infosys stakes. Mutual funds hold IT at a record-low 5.3% of their equity assets. That is the clearest disagreement between the two camps.
- Mutual funds’ biggest September buys were:
- Reliance, about ₹6,000 crore, ahead of the Jio Platforms IPO.
- BSE, over ₹5,500 crore, on its entry into the Nifty 50.
- NSE shares before its IPO.
- Private banks and Swiggy. Their biggest sales were Wipro, L&T and TCS.
- Results season backs some of this, not all. Early Q2 profits are up 25.5% across 337 companies, but metals and power drive much of it. Banks are growing profits while margins shrink, and pharma has disappointed.
- Where several signals line up (institutional buying, a decent quarter and a sane valuation), the short list is HCL Tech, Karnataka Bank, ICICI Bank, Kotak Bank and ITC. HDFC Bank goes on a separate watch list: funds keep absorbing it at its cheapest valuation in years, but its quarter was weak. These are names to research further, not buy calls.
The flow picture
The fall has two engines: FPIs selling and Indian savers buying.
| Flow | Jul 2026 | Aug 2026 | Sep 2026 | Oct 2026 (to date) |
|---|---|---|---|---|
| FPI net (₹ crore) | +20,200 | +29,631 | −35,861 | −48,056 |
| DII net (₹ crore) | +35,099 | not confirmed | +64,759 | buying on most days |
| Equity MF net inflows (₹ crore) | — | 29,329 | 38,307 | out mid-November |
| SIP inflows (₹ crore) | — | 32,297 | 32,490 (record) | — |
- September flow, in one line: FPIs sold ₹45,537 crore in the secondary market but put ₹9,676 crore into IPOs, mostly NSE’s. Domestic institutions bought for the 38th month in a row.
- Savers are buying the dip, not fleeing it. Equity fund inflows rose 31% in September. The SIP stoppage ratio fell for a fifth straight month, to 78.5%. New money went mostly to small-cap (₹9,039 crore), mid-cap (₹7,835 crore) and flexi-cap (₹6,702 crore) funds. Large-cap funds got just ₹859 crore.
- Ownership has flipped. FPIs owned 15.1% of NSE-listed companies in June 2026, the lowest in 69 quarters. Domestic institutions owned 19.5%, and mutual funds alone a record 11.6%. That gap is the widest since 2001.
- Why FPIs are selling:
- US 10-year yields above 5%.
- The rupee near 95 per dollar.
- Brent crude at $100–114 because of the West Asia conflict.
- The RBI’s rate hike to 5.50% on 7 October.
- Money chasing the AI rally in Korea and Taiwan.
- Valuations that look rich against FY27 earnings growth of around 9–10%.
- The selling is slowing. FPIs turned net buyers on 16 October, ending a 15-session streak, and bought on two days in the week to 23 October. Brokers now point to lower US yields, a firmer rupee and FII ownership already at multi-year lows. That is not yet a reversal.
Where FIIs are selling, and the one place they are buying
- Financial services was the top sale in every fortnight, ₹21,781 crore in six weeks. This is the HDFC Bank, BSE, MCX and NBFC selling seen in the shareholding data below.
- Consumption is being sold hard. FMCG (−₹8,172 crore) and autos (−₹6,533 crore) were the second- and third-largest sales in early October. That fits the worries about crude oil, the rupee and input costs that hit Nestle’s stock after results.
- IT flipped to a buy in October (+₹2,599 crore) after TCS, HCL Tech and Wipro reported in mid-October and the Nifty IT index rallied about 12% in a week. It is the only large sector FPIs bought.
- Healthcare flipped the other way, from +₹2,114 crore in early September to −₹5,497 crore in early October, as Dr Reddy’s and Torrent missed.
- Consumer services (Eternal, Swiggy, Lenskart, Meesho, travel) was bought in late September, then sold in October.
What mutual funds bought and sold in September
The latest monthly portfolios (September, published around 10 October) show where ₹38,307 crore of fresh equity money went.
Biggest net buys and sells across all funds (Prime Database and Motilal Oswal Fund Folio):
| Bought | Detail | Sold | Detail |
|---|---|---|---|
| Reliance Industries | about ₹6,000 crore, the top buy, ahead of the Jio Platforms IPO | Wipro | among the top sells; fund holdings down from 51 crore shares in Dec 2025 to 17 crore |
| BSE | over ₹5,500 crore; shares held +35%, bought in the 30 Sep block when it entered the Nifty 50 | L&T | top sell |
| NSE (pre-IPO) | about ₹3,408 crore | TCS | shares held −2.9% |
| PB Fintech (Policybazaar) | about ₹1,747 crore | Adani Ports | −5.5% |
| HDFC Bank, ICICI Bank | among the top five buys | Tata Motors PV | −4.2% |
| Swiggy | among the top five; shares held +20% | Grasim, Jio Financial | −2.5%, −2.3% |
| Dr Reddy’s, Tata Steel, Bajaj Finance, Cipla | shares held +6%, +5%, +4%, +3% | RVNL, Lodha | −42%, −25% |
| Patanjali Foods, Astral | +18%, +17% | IDBI Bank, MRPL | −45%, −34% |
| Small caps: Cupid, Bharat Coking Coal, Vedanta Power, Godawari Power, Natco | +21% to +338% | Tata Chemicals | −12% |
What the star funds did
- Parag Parikh Flexi Cap:
- Brought cash, debt and arbitrage down to 9.8% (18.9% in March), so it is putting money to work in the fall.
- Nearly quadrupled DLF to 2.5% of the fund.
- Added Bharti Airtel, M&M and Indus Towers (8 lakh to 71 lakh shares).
- Bought Petronet, IGL, MGL and Bajaj Holdings; sold out of Great Eastern Shipping.
- HDFC Flexi Cap: added HDFC Bank, ICICI Bank and Kotak Bank.
- ICICI Pru Flexi Cap: added TVS Motor (now 9.5%, its top holding) and M&M.
- SBI: SBI Large Cap added 98 lakh Kotak Bank shares; SBI Focused added Bajaj Finance and Muthoot.
- Quant Flexi Cap: more than doubled Tata Power to 6.3%.
- Banks, split views: Nippon Large Cap added HDFC Bank, while Franklin Flexi Cap cut HDFC Bank and Kotak.
- New listings: Invesco Midcap entered NSE and Groww.
Cash and sector weights
- Fund cash rose slightly to ₹1.83 lakh crore, or 3.98% of assets (3.80% in August). Funds are mostly deploying the new inflows, not hoarding them.
- IT is at a record-low 5.3% of fund equity assets, against 7.6% at the end of 2025 and 13.4% in 2021. Within IT, funds added Infosys and HCL Tech and cut Wipro.
- In October, 25 fund houses put ₹2,785 crore into the Jio Platforms anchor book, 34% of it, led by SBI Focused (₹315 crore). Reliance exposure is effectively being doubled through the IPO.
Read with care: “shares held +35%” for BSE is index-inclusion buying, and Reliance and NSE are IPO positioning. The discretionary signal is in the banks, Swiggy, the PPFAS buys and the IT switch from Wipro and TCS into Infosys and HCL.
A note on the boutique fund houses and AIFs
The newer fund houses (September portfolios)
| Fund | AUM | Cash in the fall | Added or raised | Cut or exited |
|---|---|---|---|---|
| Helios Flexi Cap (Samir Arora) | ₹8,857 cr | Deployed: about 3.1% → 1.6% | New: Kotak Bank (3.0%), ITC, Pine Labs, Netweb, Piramal Pharma. HDFC Bank 2.6% → 4.3%, Adani Ports, Coforge | Exited Solar Industries, NTPC, Welspun Corp, Axis Bank |
| Abakkus Flexi Cap (Sunil Singhania) | ₹7,844 cr | Steady at about 5.7% | Dixon, Groww, Leela Palaces, NTPC, Lupin | Trimmed ICICI Bank, M&M, SBI, Reliance |
| Old Bridge Focused (Kenneth Andrade) | ₹4,542 cr | Raised: 7.7% → 9.1% | ITC (now 4.9%), IndiGo, Redington, Tata Steel | Maruti, Prestige, Tata Motors PV; holds no IT |
| TrustMF Flexi Cap | ₹1,006 cr | Raised: 2.6% → 7.7% | Kotak Bank, Bharti Airtel, Motherson, Apollo Hospitals | Shriram Finance, Muthoot, Bajaj Finance |
In one line each:
- Unifi put cash to work (5.4% → 1.8%) and added HAL.
- Capitalmind raised cash to 4% and added Welspun Corp and MCX.
- The Wealth Company raised cash to 8% while tilting toward small caps.
The Abakkus, Old Bridge and TrustMF changes are weight changes, so they include price moves.
What it adds
- The boutiques point to the same names as the big fund houses: Kotak Bank (Helios, TrustMF), ITC (Helios new, Old Bridge raised) and HDFC Bank (Helios nearly doubled it).
- Cash shows a split. Helios and Unifi bought the fall. Old Bridge, TrustMF and The Wealth Company built cash. Singhania kept his level.
- Manager views:
- Andrade says crude near $100 narrows the opportunity set, and he has no IT.
- Singhania prefers healthcare beyond generics, new energy, platforms and data centres over IT services, staples and oil.
- Arora calls this the start of “a more favourable phase” for India after two years of underperformance.
AIFs, PMS and well-known investors
- Pros lost less in September. The average equity PMS fell 3.4% and the average Cat III AIF 2.4%, against a 6.1% Nifty fall. 77% of PMS strategies and 88% of Cat III AIFs beat their benchmarks. The best PMS made +8.4% and the worst lost 9.3%.
- Pre-IPO and IPO:
- Abakkus and Carnelian together bought 2.95% of SFC Environmental from its promoters at ₹330, about ₹91 crore, ahead of its 27–29 October IPO.
- 360 ONE put ₹100 crore into the Jio anchor book.
- September-quarter filings:
- Mukul Agrawal: about ₹191 crore into 1.3% of Tega Industries, plus four smaller new stakes.
- Dolly Khanna: returned to Rain Industries with 1.7%.
- Vijay Kedia: raised iWare Supplychain, an SME stock, to about 7.4%.
- Ashish Kacholia: cutting Xpro India, from 3.9% to 2.0% in the quarter and then another 0.9% on 19 October.
- Abakkus: reports also show new stakes in Paramount Communications (3.6%) and BEML (1.1%), each from a single source.
- What the AIF managers say:
- Vikas Khemani (Carnelian): “much of the downside may be behind us”, though the next three months could be weak. He likes small-cap healthcare, CDMO and manufacturing.
- Saurabh Mukherjea (Marcellus): Nifty is at about 18× earnings against a long-run 15×, so he expects only high-single-digit index returns and buys quality after sharp falls.
- The contrast with mutual funds: while the big fund houses bought large private banks and Reliance, the AIFs and well-known individual investors went small and specific, mostly into industrials, capex suppliers, pre-IPO stakes and SME stocks. That is higher-risk money, and their filings show up only quarterly.
Q2 shareholding: who handed what to whom
Companies filed their September-quarter shareholding by 21 October. We pulled FII and DII stakes for 52 stocks that appear in the fund, FII and block-deal news.
The handover (FIIs out, Indian institutions in):
| Stock | FII change | DII change | Price vs 52-week high | P/E |
|---|---|---|---|---|
| Swiggy | −5.1 | +7.1 | −59% | loss-making |
| BSE | −4.2 | +1.7 | −27% | 46.5 |
| Astral | −2.8 | +2.8 | −23% | 61.5 |
| MCX | −2.8 | +4.4 | −13% | 50.0 |
| HDFC Bank | −2.4 | +1.7 | −32% | 13.3 |
| Muthoot Finance | −1.9 | +1.8 | −43% | 8.4 |
| M&M | −1.6 | +1.6 | −26% | 18.6 |
| Indus Towers | −1.5 | +1.5 | −21% | 14.0 |
| Bharti Airtel | −1.0 | +1.0 | −13% | 37.8 |
HDFC Bank’s FII ownership has fallen from 48.4% to 39.4% in a year, while mutual-fund ownership rose from 26% to 31.9%.
Joint buying (both added):
| Stock | FII change | DII change | Price vs 52-week high | P/E | What drove it |
|---|---|---|---|---|---|
| EPL | +9.6 | +10.1 | −19% | 17.3 | Blackstone sold its 26% stake on 1 Sep; Quant MF, Bandhan MF, ADIA and others bought |
| Lenskart | +5.5 | +3.3 | −14% | 166 | Recent listing, investor lock-ins ending, index entries |
| Meesho | +4.7 | +4.5 | −16% | loss-making | Recent listing |
| Groww | +4.0 | +2.7 | −20% | 42.3 | Recent listing; capital-markets theme |
| Thyrocare | +3.9 | +5.0 | −30% | 40.8 | Diagnostics |
| Pine Labs | +3.7 | +4.8 | −45% | 138 | Recent listing |
| Karnataka Bank | +3.2 | +2.9 | −13% | 7.9 | Cheap old private bank |
| Torrent Pharma | +1.8 | +3.6 | −14% | 79.3 | Promoter sold 7.5 points; institutions absorbed it |
| Adani Enterprises | +1.9 | +1.3 | −24% | 141 | QIP in July (SBI MF 15%) |
| Apar Industries | +1.8 | +0.8 | −25% | 50.0 | Cables and conductors for transmission and data centres |
FIIs bought while Indian institutions sold: Welspun Corp (+8.5 / −3.6), Eternal (+3.9 / −3.0), Tech Mahindra (+2.1 / −1.2), Granules (+2.8 / −0.8, after a promoter block sale), Shyam Metalics and Nestle India.
Mutual funds alone: RHI Magnesita stands out, with domestic institutions up 11.7 points, the biggest jump in the set.
Block deals, QIPs and anchor books: who wrote the big cheques
Block deals and fundraises show real buyers, by name, at a known price. These are the largest from 1 September to 25 October:
| Date | Deal | Seller | Main buyers | Price, size |
|---|---|---|---|---|
| 8 Oct | ITC, 2.9% stake | GQG Partners | Fidelity ₹3,449 cr; ICICI Pru MF ₹2,419 cr; SBI MF ₹968 cr; Nippon MF ₹696 cr; Edelweiss MF, Mirae MF, ICICI Pru Life | ₹257.35; ₹9,395 cr |
| 30 Sep | BSE | Goldman Sachs, BNP Paribas | Mutual funds, on its Nifty 50 entry | MFs bought over ₹5,500 cr of BSE in September |
| 1 Sep | EPL, 26.4% (full exit) | Blackstone | Quant MF ₹345 cr; Bandhan MF; ICICI Pru MF; Edelweiss MF; ADIA; PSP; ABSL Insurance; 360 ONE | ₹240.57; ₹2,032 cr |
| 11 Sep | Granules, about 7 points of promoter stake | Promoter K. P. Chigurupati | Buyers not named; FII stake rose 2.8 points in the quarter | — |
| 17–22 Sep | Bharat Forge QIP | — | GIC 16.8%; ICICI Pru MF 10%; Invesco 7%; Axis MF, Mirae MF, ICICI Pru Life 5.5% each; DSP; SocGen | ₹1,890; ₹2,000 cr |
| 7–12 Oct | TD Power Systems QIP | — | Axis, Canara Robeco, ICICI Pru MFs 13.3% each; Mirae; ABSL; SocGen | ₹775; ₹600 cr |
| 14–19 Oct | Cemindia Projects QIP | — | Motilal Oswal MF 46%; Mirae; Tata MF; BOI MF; ABSL; Invesco | ₹1,108; ₹1,400 cr |
| ~16 Sep | NSE IPO anchor book | Selling shareholders | LIC group over ₹500 cr; SBI group over ₹400 cr; Goldman, Fidelity, GIC, ADIA, Norges | ₹1,785; ₹6,746 cr anchor, ₹22,569 cr issue |
| ~20 Oct | Jio Platforms IPO anchor book | Fresh issue | 25 MF houses ₹2,785 cr (34% of the anchor book); LIC ₹500 cr; GIC ₹341 cr; Schroders ₹293 cr; JPMorgan funds ₹182 cr | ₹1,119; ₹8,110 cr anchor, ₹30,213 cr issue; lists 28 Oct |
What the cheques say
- ITC is the cleanest buy signal of the fall. One foreign seller (GQG) exited at ₹257, and a long-only foreign fund (Fidelity) plus four Indian fund houses took nearly all of it. The stock is still around ₹258, within 2% of its 52-week low, at about 16× earnings.
- Indian funds are the capital market now. They took the largest share of every QIP above, a third of the Jio anchor book and over half of NSE’s. Foreign money still shows up through sovereign funds (GIC, ADIA, Norges), which buy on long horizons.
- Capex and power-equipment names are still raising money from Indian funds (Bharat Forge, TD Power, Cemindia). Funds are paying up for the investment cycle even in a falling market.
- The Jio IPO is soaking up liquidity. ₹30,213 crore had to come from somewhere, and part of the October selling in other large caps is funds raising cash for it. Watch for that money to return after listing on 28 October.
Results season: are the stocks being bought delivering?
The aggregate looks strong but is narrow.
- Profits are up 25.5% year on year across the first 337 companies to report, the best in 12 quarters, and sales are up 22.3%.
- Adani Power, Hindustan Zinc and JSW Steel alone account for about 30% of the profit increase while making only 6% of the sales.
- Brokers’ Nifty EPS estimates have barely moved: Motilal Oswal is at ₹1,233 for FY27 and has cut FY28 by 1.3%.
- Beat/miss scorecards come out in early November.
How the bought stocks reported:
| Stock | Who bought | Q2 FY27 result | Stock reaction | Verdict |
|---|---|---|---|---|
| HCL Tech | FIIs and DIIs added; MFs added shares | Profit +21%; constant-currency revenue +2.3% QoQ; bookings $3.26 bn (+27%); guidance kept | +7.7% | Flows and results agree |
| TCS | MFs trimmed | Profit beat at ₹13,884 cr; deal wins $9.6 bn; AI revenue run-rate $3.1 bn | +5.5% | Funds sold a stock that then beat |
| Infosys | MFs and FIIs nudged up | Profit +6.2%, a slight miss; FY27 guidance cut to 1–2% | US ADR −6% | Flows ran ahead of results |
| Wipro | MFs sold hard | Profit −5% QoQ; deal wins −45%; weak Q3 guidance | +6.5% anyway | Funds were right on the business |
| HDFC Bank | FIIs out, MFs in | Profit +4.7%; CASA ratio fell to 31.6%; NIM 3.16% | Down up to 2% | Weak quarter; MFs absorbing anyway |
| ICICI Bank | FIIs in, MFs bought | Profit +20%; NIM down 18 bp to 4.18%; gross NPA 1.20% | — | Solid, with margin pressure |
| Kotak Bank | MFs in (SBI bought 98 lakh shares) | Profit +29%; loans +25%; NIM down 22 bp | — | Growth strong, margins squeezed |
| Axis Bank | — | Profit +38%; NIM down 10 bp | −5% | Market punished costs |
| Bajaj Finance | MFs added shares (+4%) | Profit +29%; AUM +26%; ₹337 cr macro provision | −2.5% | Good numbers, cautious tone |
| Eternal | FIIs +3.9 points | Revenue +78%; profit +92%; Blinkit profitable at the adjusted level | — | Flows and results agree |
| Nestle India | FIIs +1.4 points | Revenue +20%; profit +36%; warned on input costs | −7 to −9% | Strong quarter, cost warning |
| Torrent Pharma | Both added (promoter sale) | Profit −9.6% | — | Flows ahead of results |
| Dr Reddy’s | MFs added shares (+6%) | Profit −36%; revenue −1.5% | — | Miss: buyers were early or wrong |
| UltraTech | — | Profit +21% but below estimates; volumes +14% | −5% | Volumes fine, costs bite |
| Hindustan Zinc, JSW Steel | Hindustan Zinc: flat stakes | Profit +142% and +225% | Faded | Commodity windfall, not a flows story |
What this says
- IT is where foreign buying and results line up best. HCL Tech and TCS beat, the sector rallied about 12%, and FPIs turned buyers. Mutual funds are still near a record-low IT weight, so domestic money could still move in.
- Banks are growing but margins are shrinking. Loan growth is 16–25%, but net interest margins fell 10–23 bp as deposits got costlier, and the RBI’s October hike will add to deposit costs. Funds are buying the large private banks on valuation, not on near-term earnings momentum.
- Pharma is where flows and results disagree. Dr Reddy’s and Torrent both missed after being bought.
- Still to report:
- This week: L&T, Maruti, Bajaj Auto, Cipla and Tata Steel on 27 Oct; HUL, Adani Ports and Adani Enterprises on 28 Oct; Asian Paints and Trent on 29 Oct; Sun Pharma and BEL on 30 Oct; NTPC on 31 Oct.
- Next week (dates not confirmed): Reliance, SBI, Bharti, ITC and M&M.
The conviction list: where the signals agree
One signal is noise: funds must deploy SIP money, index changes force buying, and promoter sales have to land somewhere. So each stock is checked against four signals:
- FII stake up in the September quarter.
- Domestic institutions’ stake up.
- Named fund-manager or block-deal buying in September–October.
- A Q2 result that held up.
Prices and P/Es are from Screener on 26 Oct 2026.
| Stock | FII | DII | Named buying | Q2 result | Score | P/E | Price vs 52-week high | What to watch |
|---|---|---|---|---|---|---|---|---|
| HCL Tech | +0.4 | +0.2 | Funds raised share count; FPIs bought IT in October | Beat; guidance kept | 4/4 | 20.3 | −20% | Deal conversion; whether funds lift IT weight from its record low |
| ICICI Bank | +0.9 | −0.6 | Top-5 MF buy in Sep; HDFC Flexi Cap added | Profit +20%; NIM down 18 bp | 3/4 | 17.0 | −6% | Deposit costs after the RBI hike |
| Kotak Bank | −0.6 | +0.8 | SBI Large Cap +98 lakh shares; HDFC Flexi Cap added | Profit +29%; NIM down 22 bp | 3/4 | 20.2 | −5% | Margins; already near its high |
| Bajaj Finance | −0.4 | +0.7 | MF shares +4%; SBI Focused added | Profit +29%; macro provision | 3/4 | 26.4 | −21% | Credit cost if the economy slows |
| ITC | −1.0 | +0.7 | ₹9,395 cr GQG block taken by Fidelity, ICICI Pru, SBI, Nippon | Due next week | 2/4, result pending | 16.4 | −39% | Cigarette volumes; FMCG input costs |
| M&M | −1.6 | +1.6 | PPFAS and ICICI Pru Flexi Cap added | Due next week | 2/4, result pending | 18.6 | −26% | Tractor and SUV demand; FPIs sold autos hard |
| Karnataka Bank | +3.2 | +2.9 | — | Not covered | 2/4 | 7.9 | −13% | Small cap; check asset quality |
| Muthoot Finance | −1.9 | +1.8 | SBI Focused added | Not covered | 2/4 | 8.4 | −43% | Gold-price swings; FII exit |
| HDFC Bank | −2.4 | +1.7 | Top-5 MF buy; HDFC and Nippon funds added | Weak: profit +4.7%, CASA down | 2/4 | 13.3 | −32% | Deposit franchise; FII weight still 39% |
| Eternal | +3.9 | −3.0 | JioBlackRock exited | Strong: profit +92% | 2/4 | 621 | −8% | Valuation leaves no room |
Joint buys that score well but cost a lot: Lenskart (P/E 166), Pine Labs (138), Meesho (loss-making) and Groww (42). FIIs and Indian funds both added, but much of it is post-IPO float, lock-in expiries and index inclusion. These are flows chasing new listings, not bargains.
How to read the list
- Highest agreement: HCL Tech and the large private banks other than HDFC Bank. Foreign and domestic money, fund managers and results mostly point the same way, and none trades above 26× earnings.
- Best value with institutional support: ITC and HDFC Bank are 32–39% off their highs at 13–16× earnings, with Indian funds absorbing foreign selling. One is waiting on results and the other just reported a weak quarter, so both need patience.
- None of these is a buy call. The list shows where institutional money and earnings agree. Your price, horizon and position size are separate decisions, and this is not investment advice.
What smart money is selling, and the traps
Both camps are selling:
- IT laggards: Wipro (funds cut holdings by two-thirds since December) and, among large caps, TCS and L&T are at the top of September’s fund sales.
- Capital-markets winners after their run: FIIs cut BSE by 4.2 points and MCX by 2.8 points, though Indian funds took both.
- Consumption: FPIs sold ₹11,173 crore of FMCG and ₹12,745 crore of autos in six weeks.
- Funds’ broad cuts: Adani Ports, Tata Motors PV, Grasim, Jio Financial, RVNL (shares held −42%), Lodha (−25%), IDBI Bank (−45%) and MRPL (−34%).
- FII exits in mid and small caps: Genus Power (−11.3 points), HEG (−4.9), LIC Housing Finance (−2.5) and ABFRL (−2.8, with domestic institutions also selling).
Traps when reading “smart money” data
- The data is stale. September portfolios and September-quarter shareholding were struck on 30 September, before October’s selling, the RBI hike and the smallcap crash in the week to 23 October.
- Forced buying is not conviction. Indian funds must invest roughly ₹38,000 crore a month and track their benchmarks. A +35% jump in fund holdings of BSE is index inclusion, not a view.
- Ownership moves are often one-off events: a promoter or private-equity sale (EPL, Granules, Torrent), a QIP (Adani Enterprises), or new listings settling into index funds (Lenskart, Meesho, Groww, Pine Labs). Check why a stake moved before reading anything into it.
- Smart money buys expensive stocks too. Several joint buys trade at 40–170× earnings, and funds bought Dr Reddy’s just before a 36% profit fall.
- The handover can reverse. If FPIs return in force, as they did in July–August, the stocks they dumped (HDFC Bank, BSE, consumption) tend to bounce hardest. If they keep selling, Indian funds’ ability to absorb rests on SIPs continuing. SIP stoppages are falling for now.
- This is a sample, not a census. The 52 stocks charted above are the ones named in fund, FII and block-deal news, not all 5,000 listed companies.
How to use this, and sources
How to use it
- Treat institutional buying as a filter for what to research, not a reason to buy. The edge is in the agreement between flows, results and price.
- Re-check in mid-November, when the October fund portfolios, the 16–31 October NSDL sector data and the brokers’ Q2 beat/miss scorecards arrive. A real change in direction will show there first.
- For SIP investors nothing here changes the playbook: keep investing. This is for people picking individual stocks.
About the data
- Shareholding changes for 52 stocks were checked against Screener.in (exchange filings) on 26 Oct 2026, along with prices, P/E ratios and 52-week ranges.
- “DII” includes mutual funds, insurers (LIC), banks and pension funds. “MF” figures are mutual funds only.
Limits
- Mutual-fund trades are only visible once a month and shareholding once a quarter, so October trades are mostly invisible until November.
- Some aggregator sources disagree on small details (for example Infosys profit of ₹7,823 crore vs ₹7,828 crore). Exchange filings win.
- The 2026 FPI total is quoted as ₹3.08 lakh crore in some reports and ₹3.12 lakh crore in others; the chart sums the monthly figures.
Main sources
- NSDL fortnightly sector-wise FPI data, 15 Oct 2026
- FPIs withdraw ₹48,056 crore in October so far (Millennium Post)
- AMFI September 2026 data (Outlook Money)
- Reliance, BSE lead mutual fund buys in September (Business Standard)
- MF September portfolio moves by cap (Motilal Oswal via TradingView)
- MF IT exposure at record low (5paisa)
- NSE India Ownership Report, June 2026
- ITC block deal, 8 Oct 2026 (Univest)
- Jio Platforms anchor book (Business Today)
- Q2 early results review (Business Standard)
- HDFC Bank FII stake falls 2.43 points (Kotak Neo)
- Stocks where FIIs and MFs both raised stakes in Q2 (Trade Brains)
Data as of 26 Oct 2026. I do not hold any of the stocks named here. This is research, not a recommendation to buy or sell, and I am not a licensed adviser; do your own research.